Thought leader interview: Patrick McManus — Ontario Sewer and Watermain Construction Association
October 5, 2026
CWN’s quarterly newsletter with the latest news, insights, and thought leadership.
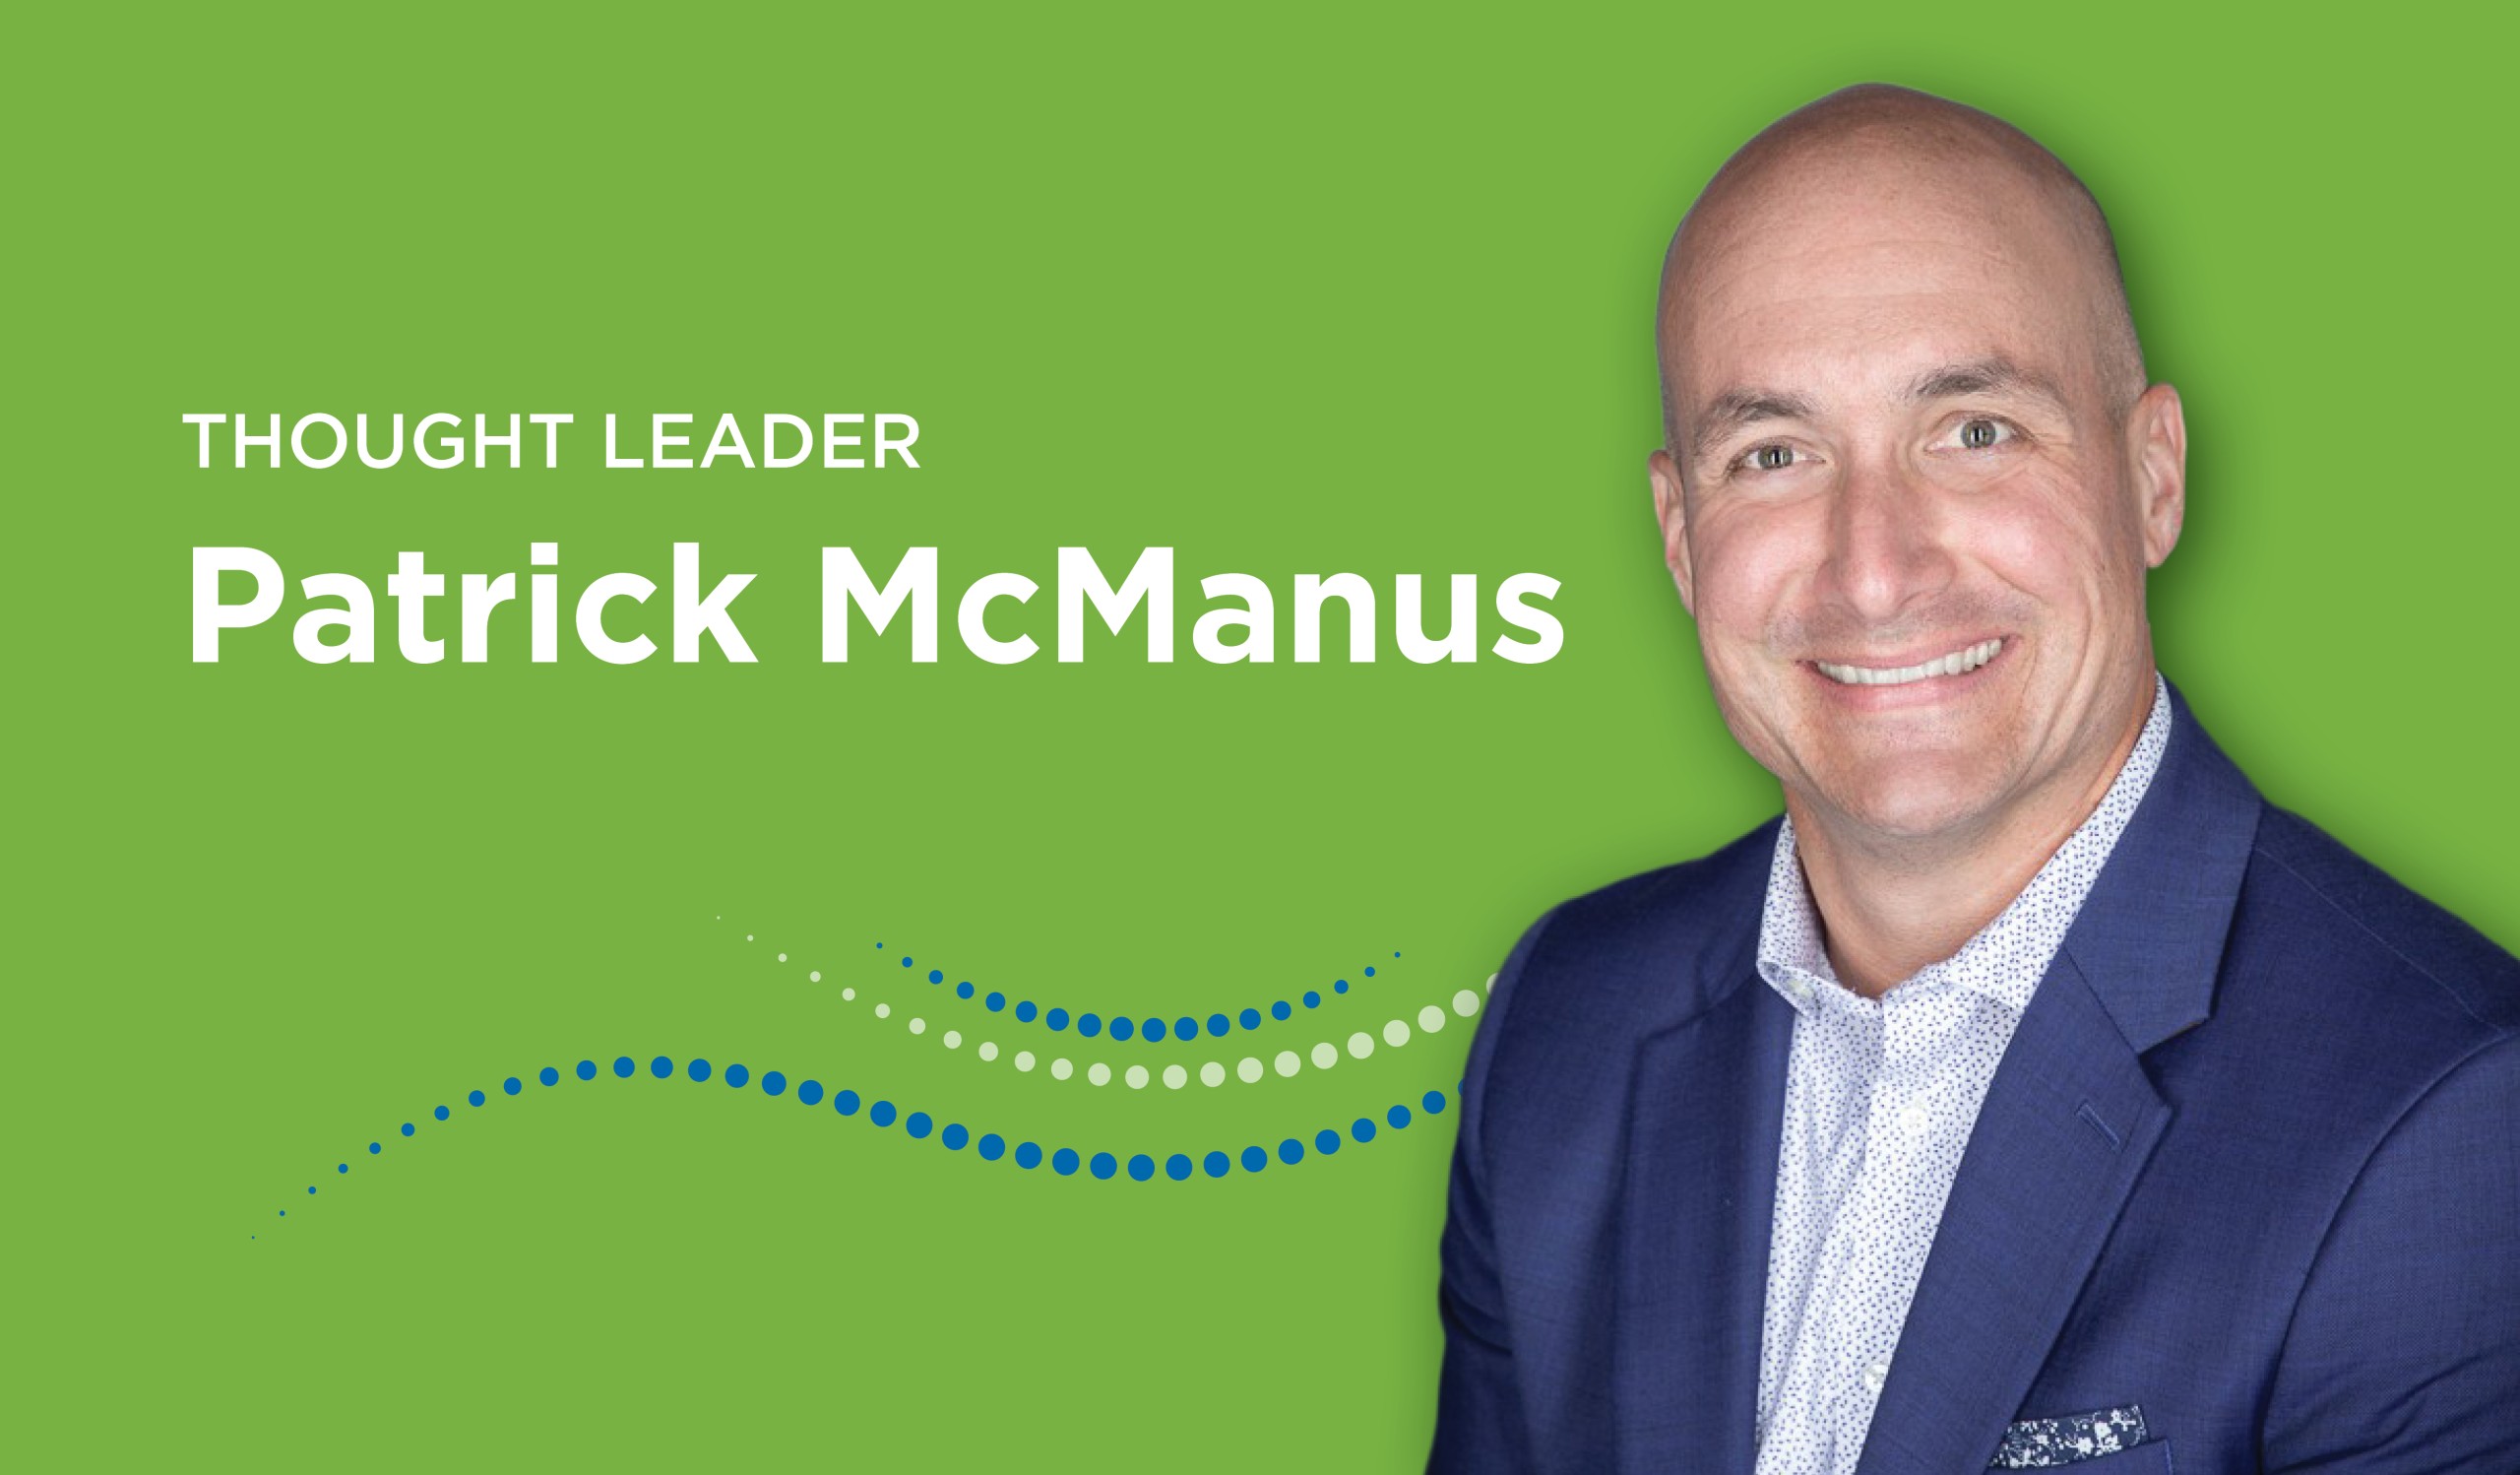
Canadian Water Network’s CEO, Nicola Crawhall, sat down for an in-depth interview with Patrick McManus, executive director of the Ontario Sewer and Watermain Construction Association (OSWCA). They examine the growing challenges of delivering water and wastewater infrastructure amid rising costs and supply chain uncertainty.
1. Can you introduce our readers to OSWCA and the national construction association?
Here in Ontario, we have 850 member companies that employ 30,000 skilled trades workers. They are the delivery arm of a huge portion of municipal capital delivery across the province. Every major urban centre has a heavy construction association, and each appoints a representative to sit on the OSWCA Board of Directors. I also sit on an advisory committee of the Canadian Construction Association, which has representatives from each provincial construction association. At that table, I see that we have shared problems, and what happens in one part of the country is coming to another part soon enough.
My role at OSWCA is to represent the industry at the provincial level, doing government relations, policy development work, labour relations, as well as some workforce development. It is interesting to work at that intersection of government policy and what happens on the construction job site. Infrastructure policy and delivery are very different. Governments announce billions of dollars in funding and set housing targets, but it is the contractors that have to transform that money and those targets into physical assets in the ground, the last mile.
2. How would you describe the current water and wastewater construction context compared to six, seven years ago (pre-COVID)?
We had our challenges back then, but it was within a more predictable environment, stable interest rates, supply chains. It feels much more complicated now. There are so many additional layers of risk that we didn’t have to consider before. Today we’re dealing with significantly higher construction costs, trade uncertainty, supply chain risk, and more complicated procurement requirements. That creates concern about the uncertainty, the risk associated with multi-year projects.
In 2019, construction companies had no idea what was in store for them when responding to requests for proposals (RFPs) that stretched into the COVID years. They continued to work, but at a much lower rate of productivity. Given the need for social distancing and staggering, our productivity was way down; we didn’t account for that risk. Contractors were left fighting in courts with municipalities and private owners to get paid for this lost productivity and these cost escalations. Liability was in the billions.
Now, the risk and liability continue with swings in energy and other costs. This time, the industry is a lot more gun-shy about new uncertainties popping up down the road, which makes them more cautious in bidding. We’re all trying to figure out the right balance on risk allocation; it’s very tricky.
At the same time, we need investment in infrastructure and build-outs more than ever. Government funding, housing needs, and aging infrastructure are contributing to construction forecasts that are shooting through the roof. We’ve got the government’s attention, and the funding is flowing, but now our concern is getting the money to market in a timely manner. Can we design and approve projects fast enough? Can industry deliver within the timelines the government expects?
3. How do construction companies bid for multi-year projects with such uncertainty?
We are observing a shakeout in the industry. We are seeing a hollowing out of the middle-class in our industry, as project size and scale seems to be either growing exceptionally large, or shrinking back to very small. Projects in the $5-$15 million range seem to be disappearing, and this is traditionally where the majority of our member companies operated. Now, given the changes we are seeing in the market, companies have to decide whether to grow their resources to bid on $50+ million projects or shrink to compete on smaller projects. It all comes down to their risk tolerance. It’s causing a pretty significant shakeout in this industry.
There’s so much price uncertainty. The cost of steel, pipe, concrete, and equipment was dependent on the global supply chain that was built up over years. All of a sudden, that supply chain is under threat. How do you forecast four to five years down the road? Mid-sized, family-owned contractors aren’t financial institutions. They are construction companies. Some struggle on the business side with all this instability, factoring in inflation and tariffs and supply chain risk.
As a result, we are seeing a lot of risk transferred down into contracts for things contractors can’t control or price. Contractors have three options when they look at contracts that have a lot of risk. They can put a lot of contingency into the bid, they can decline the bid, or they can accept the risk and potentially have a serious problem down the road. We’ve been advocating for reasonable risk contracts. Owners should be thinking about escalation clauses or other mechanisms for fuel cost and other materials right now.
4. How much interest is there in alternative project delivery and why?
There’s definitely an interest in alternative project delivery. It’s not a silver bullet, but there are really good opportunities with it. We’re seeing more alternative delivery packages in York Region, Peel, and Toronto.
Traditional design-bid-build works well for linear, low-risk projects. These alternative models are best for complicated, longer-term projects where contractors like to get involved earlier, at the design stage. That way, they can address issues that they know will cause constructability issues before design is finished.
There’s room for that experimentation, but it should be driven by the intended outcomes of the project, not simply a desire to do something differently. Sometimes the traditional model is more appropriate.
5. What lessons have you learned about the relationship between municipal utilities and construction companies? What are good practices to make a strong relationship?
The best projects tend to happen when owners and contractors work as partners. That doesn’t mean that these owners and contractors don’t disagree. They do, they will. But the relationship needs trust and a mechanism to resolve issues as they pop up. Municipalities want predictability around cost, schedule and quality. But in excavation and construction, we will always run into this conflict between project design and what we see underground after we start ripping the road up. These problems will always arise around design conflicts, and they create delays and they add cost. Unfortunately, that triggers disputes around who’s at fault and whether contractors should have anticipated the design issues or whether owners are responding quickly enough with design changes.
Contractors want good drawings, good specs, and clear decision-making when the conditions in the field change. So, in terms of lessons learned, the best owner-contractor relationships aren’t where nobody disagrees. They’re just the ones where both sides enter into a project with the understanding that design conflicts are going to occur, but that they’re going to work together to identify them early and resolve them early, because completing the project as fast as possible is a success for both sides.
6. Have your members expressed concern about the impact of tariffs and Buy Canadian/Buy Ontario policies? Have they determined what the impact of the latest round of tariffs might be on project cost escalation?
On the linear infrastructure side, we are seeing less impact from tariffs and more impact from the Buy Ontario/Canada policies. That’s because for roads, water, wastewater, sewer, our supply chains tend to be very local to begin with. Aggregate, concrete, and asphalt is all locally sourced. There are even domestic manufacturers of PVC pipe. We can’t source things like valves, fittings, and castings locally. The actual difference in domestic content in the bids is actually going to be tiny in our world. Tariff impacts hit very specific items, like structural steel for bridges or buildings. A lot was left off the tariff lists because of the impact on construction. It’s different for larger structures like waste treatment plants. Those supply chains are much more global. Ultimately, the uncertainty around what comes next in trade policy and tariffs has the worst impact. It’s scaring people and it is what’s pushing contract prices higher just because of the uncertainty.
With regard to the Buy Ontario policy, first and foremost, we support the objective. The challenge is the government’s 10 percent evaluation criteria that is adding a lot of complexity to the bidding process. We think that there’s a less administratively burdensome approach that would help local companies without adding complexity to the bidding process.